Federal Student Loan Auto Pay Offers a 1% Rate Reduction. Is It Worth Enrolling?
With everyday costs still putting pressure on household budgets, every dollar matters. A 1% interest-rate reduction will not make student debt disappear, but for eligible borrowers, it can reduce how much interest builds while the temporary benefit applies.
A 1% interest-rate reduction sounds small until you put a dollar amount on it.
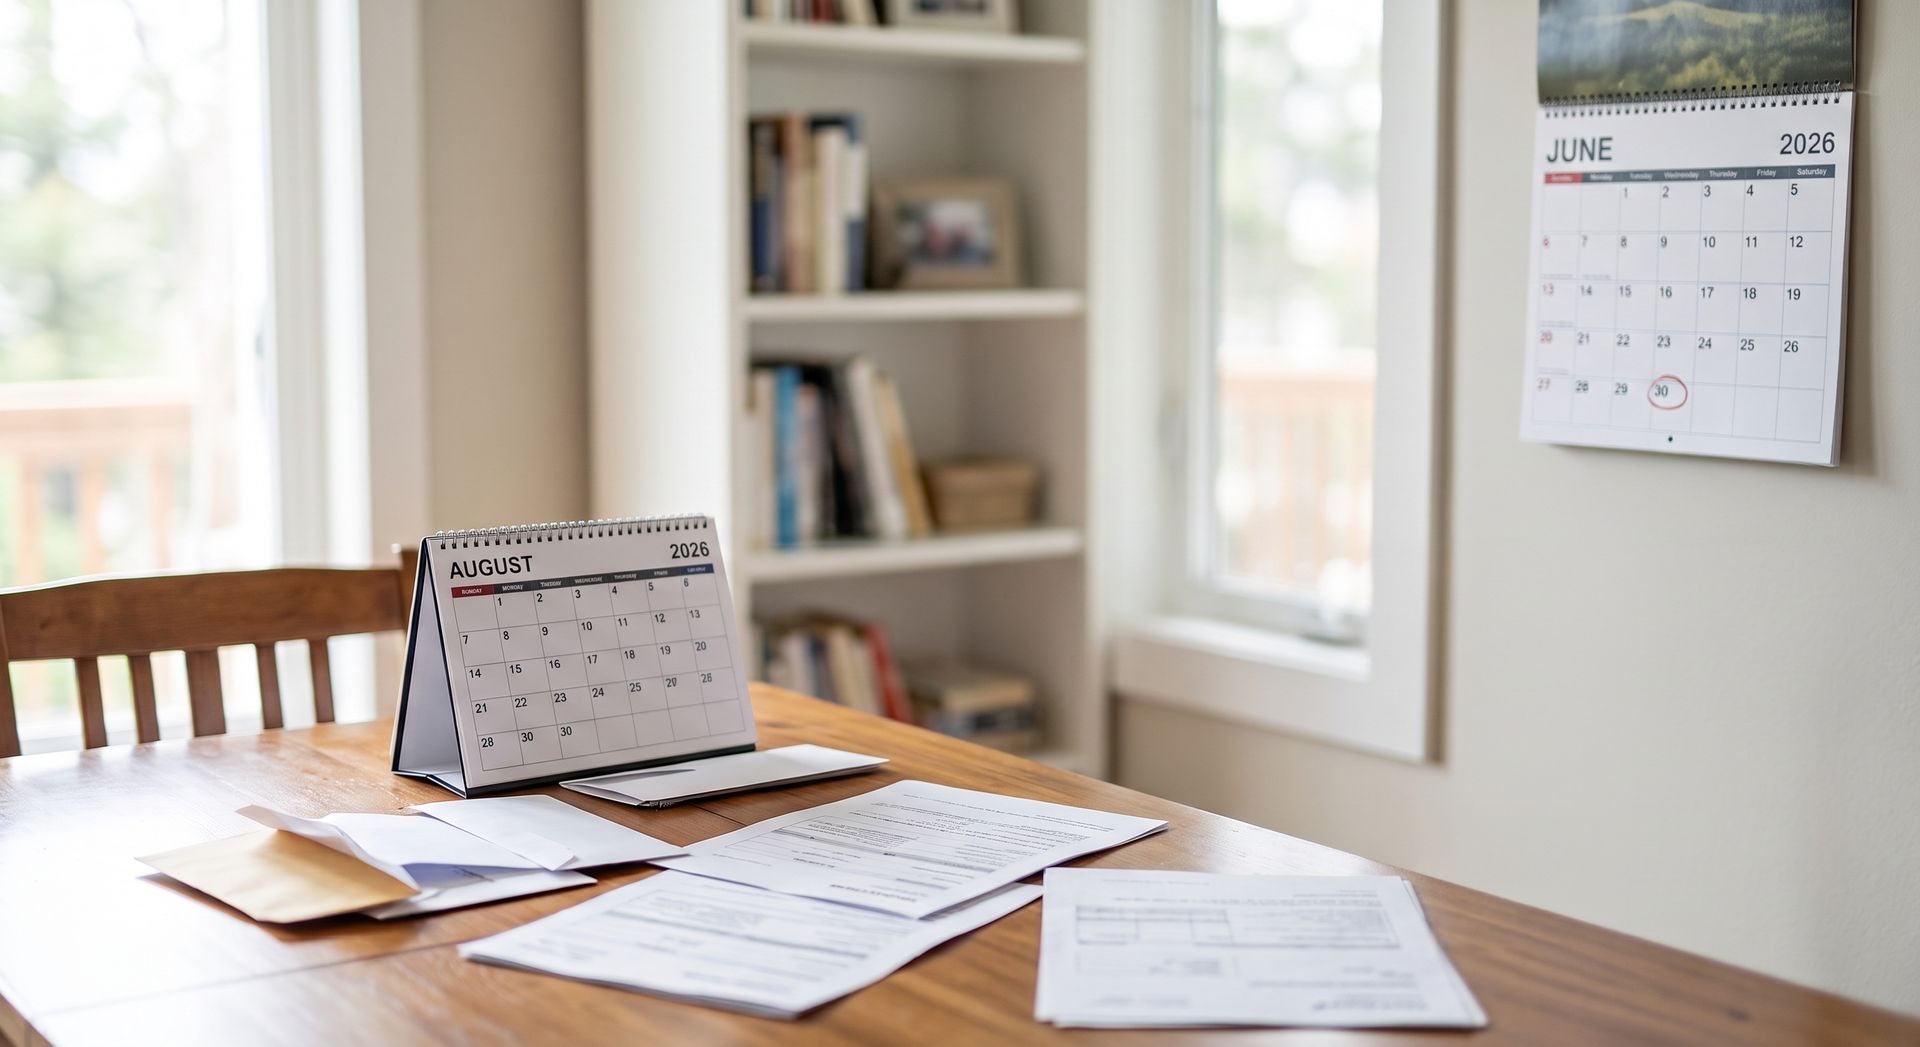
For eligible federal student loan borrowers, Auto Pay currently comes with a temporary 1 percentage point interest-rate reduction. If you are not already enrolled, the deadline for the enhanced benefit is September 30, 2026.
But there is an important distinction to understand before you sign up.
This is not 1% off your loan balance. It is not 1% off your monthly payment. It is a temporary reduction in the interest rate applied to qualifying loans while the benefit is in effect.
That can still be valuable. The question is whether automatic withdrawals fit your cash flow and whether lowering interest is actually the student loan problem you need to solve.
Quick answer: Eligible borrowers with qualifying Federal Direct Loans can receive a temporary 1% Auto Pay interest-rate reduction. Federal servicer guidance specifies Direct Loans disbursed on or after July 1, 2012. Borrowers who are not already enrolled must enroll by 11:59 p.m. ET on September 30, 2026, to receive the enhanced benefit through June 30, 2028. Whether Auto Pay makes sense depends on your eligible balance, repayment status, and ability to keep enough money in the linked bank account.
What Changed With the Federal Student Loan Auto Pay Discount?
Federal student loan Auto Pay historically came with a 0.25 percentage point interest-rate reduction.
Starting July 1, 2026, the reduction increased temporarily to 1 percentage point for eligible borrowers.
The important dates are:
Federal Student Aid says borrowers who were already enrolled in Auto Pay are included in the temporary enhanced benefit.
Is the 1% reduction permanent?
No.
The enhanced 1% reduction is a temporary benefit scheduled to run through June 30, 2028.
That distinction matters because you should not build a long-term repayment plan around the assumption that your federal loan rate will permanently remain one percentage point lower.
If the program changes again, check Federal Student Aid and your servicer for the rules that apply at that time.
Who Qualifies for the 1% Auto Pay Reduction?
Current federal servicer guidance specifies borrowers with Federal Direct Loans disbursed on or after July 1, 2012 who meet the Auto Pay requirements.
Before assuming every loan in your account qualifies, check each loan individually.
Look at:
- the loan type;
- the original disbursement date;
- whether the loan is in active repayment;
- whether Auto Pay is actually active;
- the interest rate shown for each loan after enrollment.
This is especially important if you have loans from different years or a mix of loan types.
What if my loan is in deferment or forbearance?
The interest-rate incentive applies during active repayment.
Edfinancial's federal servicing guidance states that Auto Pay drafts and the interest-rate reduction do not apply during in-school, grace, deferment, or forbearance periods.
That means enrolling in Auto Pay is not the same thing as immediately receiving the discount if your loan is currently paused.
Check your actual account status rather than relying only on your enrollment request.
How Much Could a 1% Rate Reduction Actually Save?
A simple way to understand the potential value is to look at what one percentage point of annual interest represents on a balance that stayed unchanged for a full year.
balance
*These are simplified illustrations. Your real savings will be different because your principal normally changes as you make payments. Results also depend on timing, account status, repayment plan, capitalization, and how payments are allocated.
The purpose of the table is not to promise a specific savings amount. It is to translate "1%" into an understandable scale.
Already had the old 0.25% Auto Pay discount?
Then your incremental improvement is not a full additional percentage point.
The reduction increased from 0.25% to 1%.
That means the additional reduction compared with the prior Auto Pay benefit is 0.75 percentage points.
Using the same simplified static-balance illustration:
*Illustrative only. Actual interest savings change as principal is repaid and depend on the loan's status and payment history.
That distinction is easy to miss when headlines describe the policy simply as a "1% discount."
Does Auto Pay Lower Your Monthly Student Loan Payment?
Generally, the important benefit here is the lower interest rate, not a lower required monthly payment.
Those are two different financial problems.
If your payment is affordable and your goal is reducing interest cost, Auto Pay may help.
If your required payment itself is too high for your income, enrolling in automatic withdrawals does not fix the affordability problem. You may need to review your federal repayment options instead.
This is why borrowers should separate two questions:
How can I reduce my interest cost?
from:
How can I lower my required monthly student loan payment?
If the second question is your real concern, review Docupop's guide to lower your student loan payment before treating Auto Pay as the solution.
Can You Use Auto Pay With an Income-Driven Repayment Plan?
Yes.
Federal Student Aid states that borrowers can enroll in Auto Pay while using an income-driven repayment plan.
The two tools solve different problems.
An income-driven plan determines how your required payment is calculated under the rules of that plan.
Auto Pay determines how that payment is withdrawn and, for eligible loans during the temporary program, can reduce the applicable interest rate.
You do not necessarily have to choose one or the other.
However, repayment-plan eligibility has changed significantly in 2026. Do not assume that every IDR plan is available to every borrower. Loan type, borrowing date, consolidation date, and other factors can affect which plans are available.
If your payment needs to change, evaluate the repayment plan first. Then decide whether Auto Pay works with your banking and cash-flow situation.
What Are the Downsides of Auto Pay?
The interest-rate benefit is real, but automatic withdrawal is still a cash-flow commitment.
1. You need enough money in the linked account
A payment that drafts automatically can create a problem if your paycheck arrives late, your income varies, or another large expense hits the account first.
Edfinancial states that if an Auto Pay withdrawal is rejected for insufficient funds, the borrower may need to make the payment manually. Multiple insufficient-funds occurrences may result in termination of Auto Pay and loss of the interest-rate incentive.
The interest reduction is not worth creating repeated overdraft or insufficient-funds problems.
2. Automatic does not mean you can stop monitoring the loan
You should still check:
- the amount scheduled to be withdrawn;
- the withdrawal date;
- the bank account being used;
- your current repayment plan;
- notices from your servicer;
- whether Auto Pay remains active;
- the interest rate shown on each qualifying loan.
A servicer can only act on the information in your account. Changes to repayment plans, payment amounts, bank information, or loan status can affect what happens next.
3. Auto Pay does not make an unaffordable payment affordable
Suppose your federal student loan payment is $650 per month and your budget can realistically support only $350.
Automatically drafting the $650 does not solve the underlying problem.
In that situation, the more important task may be reviewing repayment-plan eligibility and preparing the correct application.
Auto Pay is a payment mechanism with an interest incentive. It is not a substitute for repayment planning.
4. Your payment amount is subject to change
Being enrolled in an Income-Driven Repayment Plan requires an annual recertification of your income.
Failure to complete this renewal on time could result in your payment increasing to your 10-year Standard amount. For many borrowers, this payment is more than they can afford.
Automatic payments won’t stop if you fail to renew your Income-Driven Plan. You will instead be automatically debited for the new, higher amount.
Monitoring your account for changes and anticipating important deadlines becomes that much more crucial when you’re enrolled in Auto Pay.
5. A repayment pause changes the picture
If your loans enter a qualifying deferment or forbearance, automatic drafts may pause and the interest-rate incentive may not apply during that period.
Borrowers moving into or out of a repayment pause should verify the status with their servicer rather than assuming their previous Auto Pay setup is operating normally.
What If You Are Already Enrolled in Auto Pay?
Federal Student Aid says borrowers who were already enrolled are included in the enhanced temporary benefit.
You should not need to re-enroll solely to receive the 1% reduction.
Still, verify what happened on your own account.
Check:
- Which loans show Auto Pay as active.
- Which loans meet the eligibility requirements.
- The interest rate currently displayed for each loan.
- The scheduled withdrawal amount and date.
- Whether any loan is in a status where Auto Pay is paused.
Borrower accounts can contain loans from different time periods. Do not assume one account-level message means every individual loan is being treated identically.
Should You Enroll Before September 30?
There is no universal answer.
Auto Pay may fit well when:
- you have qualifying loans;
- your loans are in active repayment;
- you already intend to make every required payment;
- you reliably keep enough money in the linked bank account;
- reducing interest cost supports your repayment strategy;
- you are comfortable monitoring automatic withdrawals.
Think more carefully when:
- your required payment is currently unaffordable;
- your income varies significantly;
- the timing of the withdrawal could cause cash-flow problems;
- you are changing repayment plans;
- you are moving into or out of deferment or forbearance;
- you are trying to resolve delinquency or default;
- you have not confirmed which loans actually qualify.
The question is not simply, "Is a lower interest rate good?"
The more useful question is:
Does this lower interest rate fit the repayment strategy and cash flow I already need?
If the answer is yes and your loans qualify, Auto Pay can reduce the amount of interest accruing while the temporary benefit applies.
If the answer is no because the payment itself is the problem, evaluate that problem first.
How to Enroll in Federal Student Loan Auto Pay
Enrollment is handled through your federal student loan servicer.
Federal Student Aid currently identifies federal servicers including Aidvantage, CRI, Edfinancial, MOHELA, and Nelnet.
The basic process is:
- Log in to your federal loan servicer account.
- Find the Auto Pay or automatic payment section.
- Review the loans being included.
- Confirm the checking or savings account.
- Review the amount scheduled to draft.
- Review the draft date.
- Submit the enrollment request.
- Confirm that Auto Pay becomes active.
Do not stop making required payments simply because you submitted an Auto Pay request. Follow your servicer's instructions until the first automatic payment is confirmed.
And remember: federal Auto Pay enrollment itself is free.
What If My Real Problem Is the Monthly Payment?
This is where the Auto Pay decision can reveal a bigger issue.
If your current payment works for your budget, the temporary interest reduction may be the main decision.
If your payment does not work for your budget, start with your repayment options.
Depending on your loans and eligibility, that review may involve:
- an income-driven repayment application;
- federal loan consolidation;
- PSLF documentation and payment tracking;
- resolving a default through the appropriate federal process.
Those decisions can involve more paperwork and more consequences than simply turning on Auto Pay.
Docupop provides paid third-party document preparation assistance for borrowers who want help organizing and preparing federal student loan applications. You can also complete federal applications yourself for free through official government channels.
Frequently Asked Questions
Is the federal student loan Auto Pay discount really 1%?
For eligible loans, yes. The temporary enhanced Auto Pay benefit is a 1 percentage point interest-rate reduction. It is not 1% off your balance or 1% off the amount of your monthly payment.
When is the deadline for the 1% Auto Pay benefit?
Borrowers who are not already enrolled must enroll by 11:59 p.m. ET on September 30, 2026, under current federal servicer guidance.
How long does the 1% Auto Pay reduction last?
The temporary enhanced benefit is currently scheduled to continue through June 30, 2028, as long as the borrower and loan continue to meet the applicable requirements.
Can I use Auto Pay while on RAP or another IDR plan?
Federal Student Aid says borrowers can use Auto Pay while on an income-driven repayment plan. Whether RAP, IBR, or another plan is available to you is a separate eligibility question based on your federal loan history and current rules.
Do I get the 1% reduction while my loans are in forbearance?
Federal servicer guidance states that the Auto Pay rate reduction applies during active repayment and is not provided during in-school, grace, deferment, or forbearance periods.
Does Auto Pay lower my monthly student loan payment?
The 1% benefit reduces the applicable interest rate. It should not be confused with moving to a repayment plan designed to change the required monthly payment.
What happens if an Auto Pay withdrawal fails?
If your bank rejects the withdrawal, you may need to make the payment manually. Repeated insufficient-funds problems may cause your Auto Pay agreement to be terminated and the rate incentive to be lost.
I am already enrolled in Auto Pay. Do I need to enroll again?
Federal Student Aid says borrowers already enrolled are included in the enhanced temporary benefit. Verify the status and displayed rate for your individual loans in your servicer account.
A 1 percentage point interest-rate reduction can be meaningful, especially on a larger eligible federal loan balance.
But the best use of the benefit is straightforward: it should make an otherwise appropriate repayment strategy a little less expensive.
It should not push you into automatic withdrawals you cannot reliably fund, and it should not distract from a monthly payment that is already unaffordable.
Check your loan type, disbursement date, repayment status, bank cash flow, and current payment before making the decision.
If your bigger question is whether your federal repayment plan, consolidation status, PSLF paperwork, or default-resolution documents need attention, review those issues separately before making your next move.
Not sure whether lowering your rate or lowering your monthly payment matters more? Review your federal student loan options before you make the next paperwork decision.